

The Informal Economy Processes Billions. Its Payment Infrastructure Hasn't Caught Up.
South Africa's informal economy is large, productive, and largely invisible in mainstream financial conversations.
It employs millions of people. It serves communities that formal retail often doesn't reach. And it processes enormous volumes of real economic activity every single day through cash, through mobile transfers, through informal credit arrangements that have persisted for generations.
What it doesn't have, broadly speaking, is payment infrastructure designed for it.
What the Informal Economy Actually Looks Like
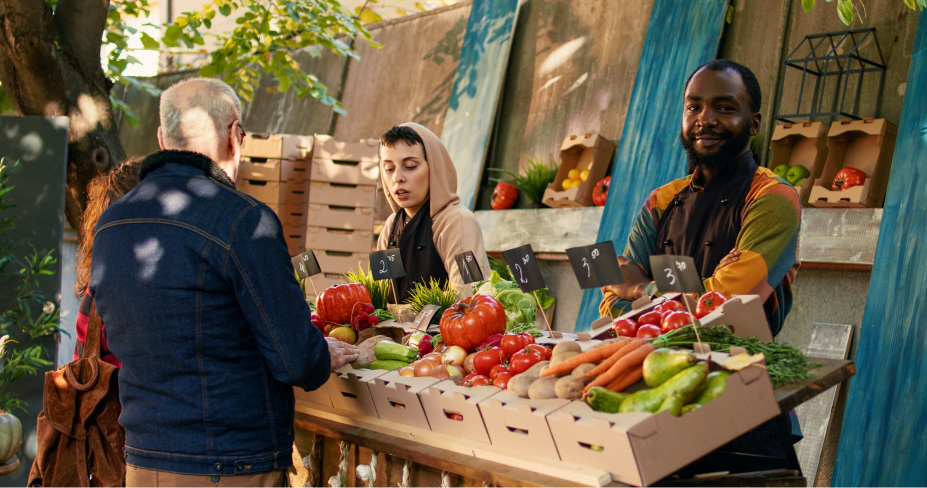
The informal economy in South Africa isn't a monolith. It includes street traders and market vendors. Spaza shops that serve as the primary grocery retail for entire township communities. Hair salons, mechanics, domestic workers, food stalls, and thousands of micro-businesses operating without fixed premises or formal retail infrastructure.
These businesses have customers. They have real revenue. Many of them operate at volumes that, in a formal retail context, would easily justify digital payment infrastructure.
What they've typically lacked is a payment product designed for their reality rather than a formal retail product loosely adapted for it.
The Card Terminal Model Doesn't Work Here
The standard digital payment onboarding model in South Africa is card-machine-first. You sign up with a provider. A terminal gets delivered. You sign a rental contract and pay a monthly hardware fee. You install it, configure it, and manage it and if you move between trading locations, or if the terminal fails, or if the monthly fee doesn't make sense at your volume, the model breaks.
For an informal trader operating from a market stall or a street corner, the card terminal model creates barriers that were never designed to be removed. It was designed for a fixed-premises business with predictable monthly volumes and a business account.
What QR-First Means for Informal Traders
QR payments change the access model fundamentally.
No hardware. No rental fee. No fixed premises requirement. A merchant can receive digital payments with a printed QR code, or even just a phone with a code displayed on screen. Set up takes minutes. The transaction fee applies only when a sale happens, there's no standing cost for being in the system.
For a market trader who does R5,000 on a good Saturday, that model is viable where a card terminal rental contract isn't. For a domestic worker who wants to accept bank transfers without sharing account details, a QR code is simpler and safer than any alternative.
Why Moving First Matters
PayInc (the operator of PayShap, South Africa's real-time payment rail) has explicitly named the informal economy as its key measure of success in the merchant payment space. Regulatory direction, technology investment, and product development are all pointing toward bringing more informal traders into the digital payment ecosystem.
This is the early phase of that shift. The traders and small merchants who adopt digital payments now are the ones who establish the customer habit, the business routine, and the digital payment history that will open other financial services to them over time.
Accepting digital payments isn't just a checkout upgrade. For informal economy businesses, it's the first step into a financial infrastructure that has historically been built for everyone else.